33. Weekly Market Recap: Key Movements & Insights
Auto Tariffs Hit the Gas, Markets Hit the Brakes!

Market Momentum Wavers Amid Tariff Concerns and Inflation Worries
Stocks experienced a volatile trading week, initially building on previous momentum before succumbing to renewed pressures. The S&P 500 started strong with a robust 1.8% gain on Monday, as investors responded positively to speculation about potentially softer tariff implementations. However, the optimism proved short-lived as policy developments and inflation concerns took center stage later in the week.
White House Policy Shifts Markets
Thursday brought significant market turbulence following the White House's unexpected announcement of 25% tariffs on all foreign-made automobiles. The news, which came a week ahead of schedule, sent automotive stocks tumbling. The situation was further complicated by the inclusion of car parts in the tariff framework, a move that caught many industry observers off guard. Friday saw additional pressure as inflation worries resurfaced, contributing to a nearly 2% market decline and bringing the S&P 500's weekly loss to 2.7%.
Sector performance showed notable divergence, with consumer durables, retail trade, and communications emerging as relative outperformers. Health technology, utilities, and electronic technology lagged. In corporate news, GameStop captured attention with a 17% surge on cryptocurrency acquisition speculation, though the enthusiasm proved fleeting as the stock ultimately closed down 14.6% for the week.
Wall Street's Measured Response to Auto Tariffs
Despite the significant implications of the new auto tariffs, market reaction has been relatively measured, reflecting investors' growing adaptation to policy uncertainty. While automotive stocks faced immediate pressure, the broader market impact was initially contained as traders balanced multiple factors. Industry analysts project vehicle cost increases ranging from $2,000 to $10,000, with implementation expected within weeks. The situation is particularly complex given the global nature of auto manufacturing – even iconic American vehicles like the Ford F-150 contain just 45% domestic or Canadian-made components.
Upcoming Key Events:
Monday, March 31:
Earnings: Mitsubishi Heavy Industries, Ltd. (7011)
Economic Data: None
Tuesday, April 1:
Earnings: Cal-Maine Foods (CALM)
Economic Data: ISM manufacturing index
Wednesday, April 2:
Earnings: Levi Strauss (LEVI), UniFirst (UNF)
Economic Data: EIA petroleum status report
Thursday, April 3:
Earnings: Conagra Brands (CAG), Acuity Brands (AYI)
Economic Data: International trade in goods and services, Jobless claims, EIA natural gas report
Friday, April 4:
Earnings: Greenbrier Companies (GBX)
Economic Data: Employment situation

⚡ AI-optimized, human-verified: Our expert team carefully selected Premium market intelligence from Finchat.io data. Explore now →
Index Insights: How Major Benchmarks Performed Last Week
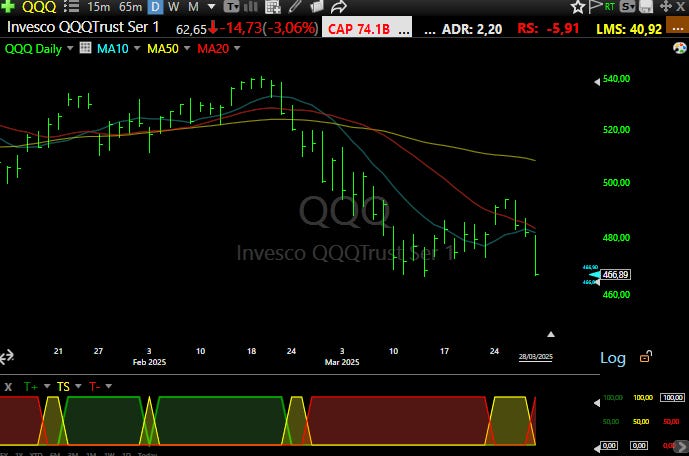
Price>MA10: 🔴
Price>MA20: 🔴
MA10>MA20: 🔴
Market Trend: 🔴 (When Price and Moving Averages are all green, the Market Trend will also be green and positive)
Trend Signal: 🔴
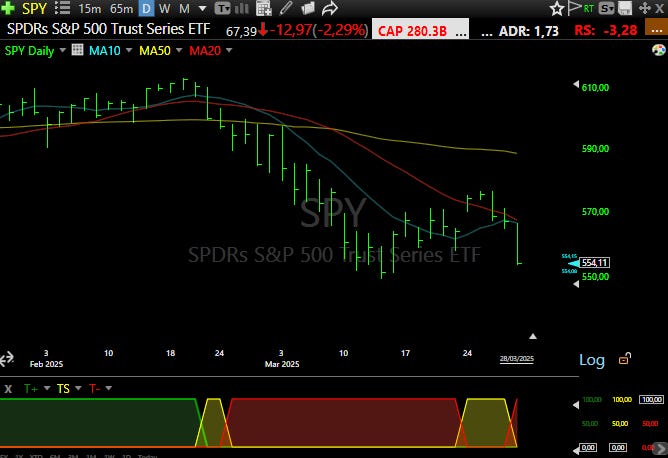
Price>MA10:🔴
Price>MA20: 🔴
MA10>MA20: 🔴
Market Trend: 🔴
Trend Signal: 🔴
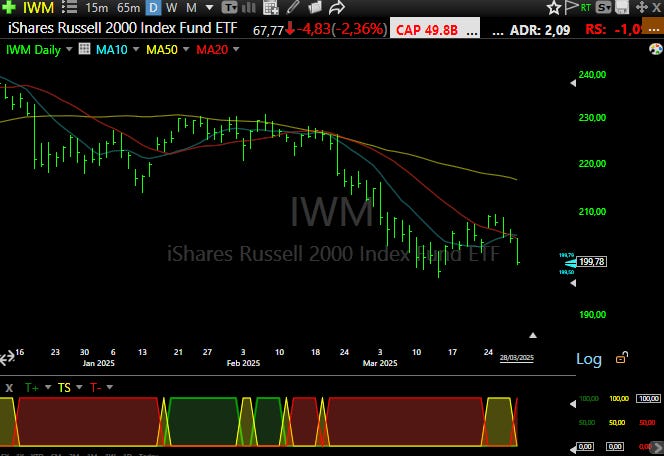
Price>MA10: 🔴
Price>MA20: 🔴
MA10>MA20: 🔴
Market Trend: 🔴
Trend Signal: 🔴
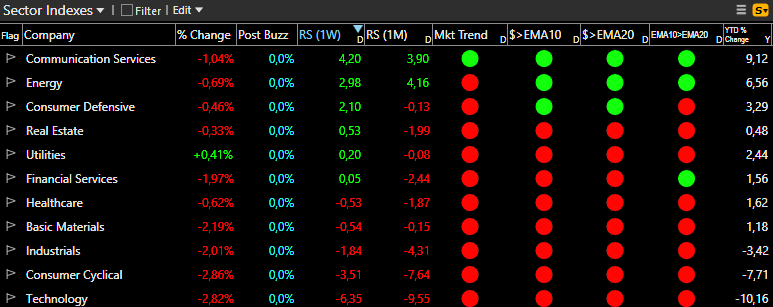
Sector Performance: Winners and Losers from Last Week
Put the market on autopilot, experience the Best Platform with TC2000
Explore now →
Winners
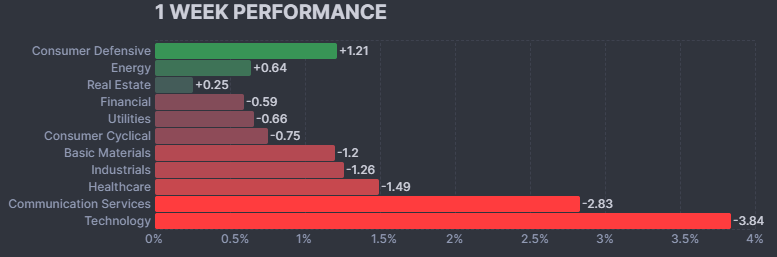
🛒 Consumer Defensive (+1.21%)
Leading all sectors with impressive gains, showing strong defensive positioning in the market.
🔋 Energy (+0.64%)
Second-best performer with solid gains, demonstrating resilience amid geopolitical tensions.
🏢 Real Estate (+0.25%)
Modest positive returns, suggesting some stability returning to property markets.
Losers
💻 Technology (-3.84%)
Largest decline of all sectors, continuing recent weakness in high-growth names.
📱 Communication Services (-2.83%)
Significant losses, reflecting investor concerns about advertising revenues and growth prospects.
🏥 Healthcare (-1.49%)
Notable decline despite traditionally defensive characteristics, pressured by policy uncertainties.
🏭 Industrials (-1.26%)
Weakness persists amid concerns about the global manufacturing outlook.
🧪 Basic Materials (-1.2%)
Continued pressure as commodity demand forecasts remain uncertain.
🌟 Weekly Industry Leaders: Energy and Metals Surge
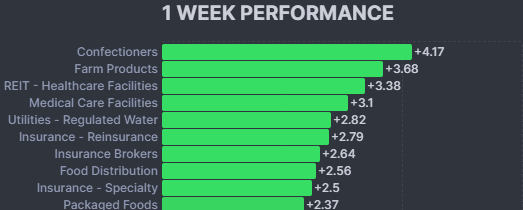
🍬 Confectioners (+4.17%)
Leading the market with impressive gains and showing strong consumer demand.
🚜 Farm Products (+3.68%)
Agricultural commodities are posting solid returns, reflecting strength in the food production sector.
🏥 REIT - Healthcare Facilities (+3.38%)
Healthcare real estate investments are delivering robust performance amid sector stability.
🏢 Medical Care Facilities (+3.1%)
Healthcare service providers are showing healthy gains as the demand for medical services remains strong.
💧 Utilities - Regulated Water (+2.82%)
Essential water service providers demonstrating resilience with steady positive returns.
🔒 Insurance - Restaurant (+2.78%)
Specialized insurance providers for the food service industry posting notable gains.
💼 Insurance Brokers (+2.64%)
Financial intermediaries in the insurance sector showing solid performance.
🚚 Food Distribution (+2.56%)
Supply chain companies for food products are maintaining positive momentum.
🛡️ Insurance - Specialty (+2.5%)
Niche insurance providers are rounding out strong performances across the insurance sector.
📦 Packaged Foods (+2.37%)
Consumer staples companies are completing the top performers with healthy returns.
🚀 Market Movers: AI Investments and FDA Clearances Drive Explosive Gains
MLGO MicroAlgo Inc (+582.14%)
📈 Strategic Investment: WIMI Hologram Cloud Inc. increased its stake to 67.65% and committed to a ten-year lock-up period for all currently owned MicroAlgo shares, signaling long-term confidence in the AI technology firm.
GDHG Gold Heaven Group Holdings Ltd (+243.06%)
💹 Speculative Trading: Shares surged despite analysts flagging concerning patterns similar to previous volatile trading episodes, suggesting a cautious approach for retail investors (Pump & Dump)
IMTE Integrated Media Technology Limited (+238.95%)
📱 Momentum Trading: The Stock skyrocketed on no apparent catalyst, with technical traders possibly driving price action in the absence of fundamental developments.
VVPR Vivopower International PLC (+202.33%)
💰 Acquisition Interest: Granted exclusivity to Energi following increased non-binding all-cash takeover offer valuing the company at US$180 million enterprise value, boosting investor confidence.
TNON Tenon Medical Inc (+138.00%)
🏥 FDA Approval: Announced FDA clearance of Catamaran® SI Joint Fusion System for new indication to augment spinal fusion, expanding potential market reach and treatment applications.
🔻 Biggest Decliners: Bankruptcy Filings and Dilution Concerns Devastate Valuations
WLGS Wang & Lee Group Inc (-94.86%)
💸 Massive Dilution: Completed two consecutive stock offerings on March 24-25 totaling more than $15 million, severely impacting share value through significant dilution.
ME 23andMe Holding Co (-72.20%)
📉 Bankruptcy Filing: Filed for bankruptcy protection, raising serious concerns about the security and future of its extensive personal health information database.
TDTH Trident Digital Tech Holdings Ltd ADS (-70.21%)
⚠️ Market Skepticism: Dramatic decline amid growing investor concerns about company fundamentals and trading patterns suggesting potential market manipulation.
MURA Mural Oncology Limited (-69.35%)
🧪 Clinical Failure: Stock collapsed after halting the Phase 3 ARTISTRY-7 trial for nemvaleukin alfa due to failure to demonstrate significant overall survival benefits, delaying NDA submission and raising questions about the drug's efficacy across all indications.
IBO Impact BioMedical Inc (-67.94%)
📊 Market Correction: The Company issued a statement confirming no material developments in business affairs, suggesting recent price movements were speculative rather than based on fundamental changes.
🌱 Support Our Work: Buy Us a Coffee or Shop Our Services! 🌱
Your small gesture fuels our big dreams. Click below to make a difference today.
[☕ Buy Us a Coffee]
[🛒 Visit Our Shop]

Questo pezzo era gratuito. Il prossimo arriva domenica.This piece was free. The next one lands on Sunday.
Dieci nomi con i livelli, la lettura del mercato, la chat con le posizioni in diretta. Con l'abbonamento leggi tutto; senza, ricevi la parte gratuita via email.Ten names with their levels, the market read, the chat with live positions. Subscribers read everything; free readers get the free part by email.