
2. Weekly Market Recap: Key Movements & Insights
Powell's Message: Is the Market Ready to Break Out?

US equity funds experienced large inflows as investors grew optimistic about potential rate cuts, driven by easing economic growth concerns. This optimism reflects hopes that the Federal Reserve may shift from its tightening stance, potentially leading to a soft landing. However, caution remains as markets await further Fed signals.
Index Insights: How Major Benchmarks Performed Last Week
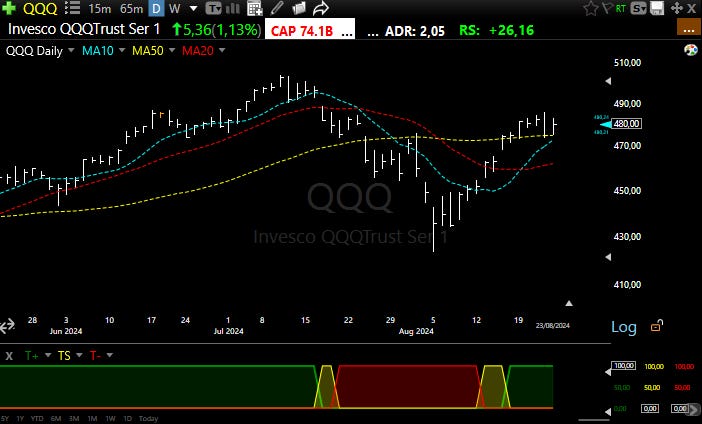
Price>MA10: 🟢
Price>MA20: 🟢
MA10>MA20: 🟢
Market Trend: 🟢 (When Price and Moving Averages are all green, also the Market Trend will be green and positive)
Trend Signal: 🟢
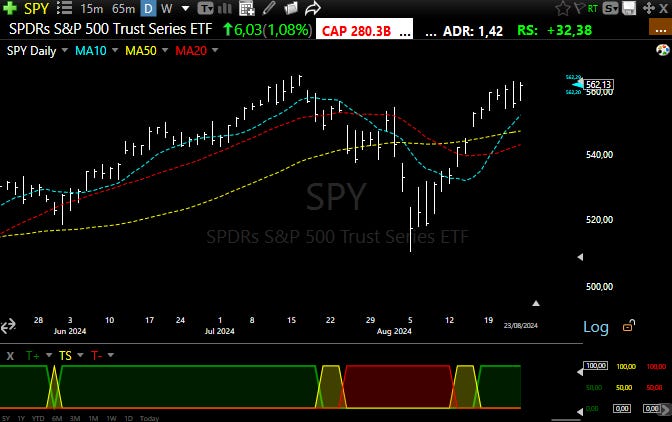
Price>MA10: 🟢
Price>MA20: 🟢
MA10>MA20: 🟢
Market Trend: 🟢
Trend Signal: 🟢
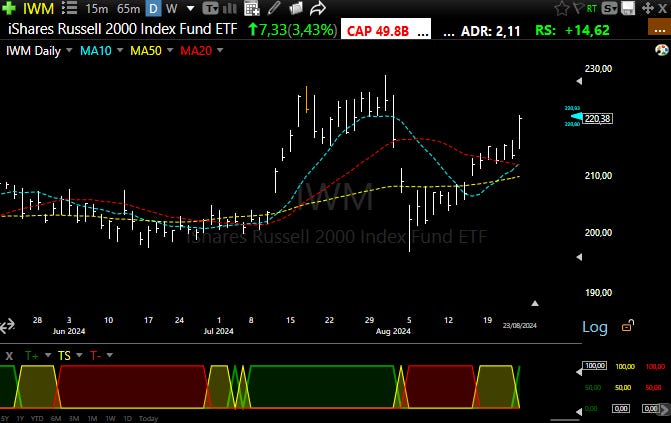
Price>MA10: 🟢
Price>MA20: 🟢
MA10>MA20: 🟢
Market Trend: 🟢
Trend Signal: 🟢
Small Caps Shine After Powell: Is the Rally Just Getting Started?
Following Powell's speech at Jackson Hole, the markets pushed higher, with a surprising leader—small-cap stocks, as evidenced by the IWM's major move. The rally has sparked optimism that small caps might be the play for the coming months, particularly if the Fed delivers on anticipated rate cuts within the next 6-12 months.
Our trend system has also shifted from Yellow to Green on the IWM index.
However, seasoned traders know that a healthy period of consolidation might be needed before charging toward new all-time highs. It’s all about patience and watching those small caps closely for now.
Financial Sector Performance: Winners and Losers from Last Week
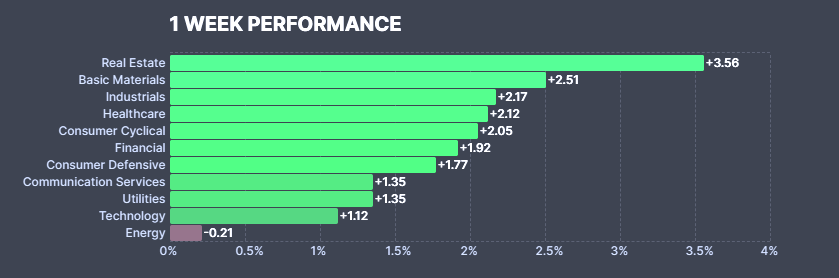
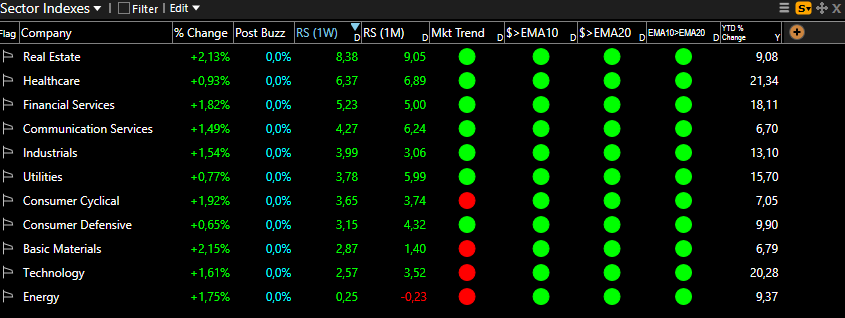
🏠 Real Estate and Healthcare 🌡️ Lead the Pack
This week, the Technology sector, which led the markets last week, found itself lagging, highlighting the volatile nature of market leadership. In contrast, the Real Estate sector emerged as the strongest performer, showcasing both impressive Relative Strength (RS) and overall weekly gains. Healthcare also made significant strides, proving resilient in uncertain times.
🧱 Basic Materials: Some Shine, Some Struggle 🌪️
Despite being the second-best performer, the Basic Materials sector has a low RS. However, the Building Materials and Lumber industries are shining, with RS values of 5.97 and 7.38, respectively. Gold continues to hold strong with an RS of 7.11, making it a bright spot in the sector.
⛽ Energy: The Market's Weak Link 🔻
Energy remains the weakest sector, not just this week but over the past month and three-month periods. The ongoing struggles stem from concerns over global demand, supply issues, and potential oversupply from OPEC, which have all contributed to its poor performance.
Residential Construction Tops the Charts: Weekly Industry Standouts with a Uranium Surprise
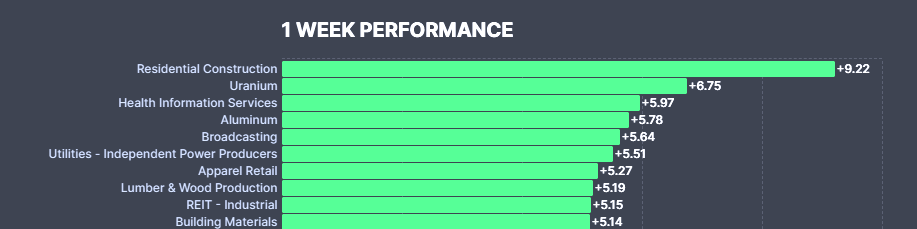
Residential Construction nailed this week with a 9.22% gain, proving that building homes still delivers. Right behind, Uranium had a glowing 6.75% surge, showing that nuclear energy was heating up. Health Information Services also saw a healthy 5.97% bump, highlighting the resilience of this digital age sector. With Aluminum and Broadcasting also making gains, it was a week of steady climbers and surprising winners, giving investors something solid to build on.
Selected stock moves (19–23 August 2024)
Weekly changes compare the August 16 and August 23 closes. Friday declines compare August 22 with August 23. Prices are adjusted for stock splits and exclude dividends.
Selected weekly moves
Applied DNA Sciences, Inc. (APDN) +225.64%
Applied DNA said on August 19 that it planned to seek New York State authorization to extend its Linea mpox assay to clade I. Validation was still under way.Virax Biolabs Group Limited (VRAX) +155.87%
The backdrop was the mpox emergency declared by the WHO on August 14.GD Culture Group Limited (GDC) +172.50%
GDC’s rally accelerated on Wednesday and Thursday, before Friday’s pullback.GeoVax Labs, Inc. (GOVX) -9.49%
GeoVax announced an August 23 investor webinar on mpox, covering its spread, prevention and treatment.
Portage Biotech (PRTG) +118.18%
Portage’s August 14 annual report described paused enrollment in its sponsored adenosine trials and a review of strategic alternatives.
Friday declines (23 August 2024)
U-BX Technology (UBXG) -92.63%
U-BX disclosed a change of auditor on August 21, 2024, appointing HTL International to replace Wei, Wei & Co.Farmmi (FAMI) -57.89%
Farmmi announced a roughly $1 million share offering with accompanying warrants on August 23.GD Culture Group (GDC) -29.68%
Friday’s decline reduced the gains accumulated earlier in the week.Nuwellis (NUWE) -26.16%
Nuwellis reported Q2 revenue of $2.2 million and a $7.7 million net loss attributable to common shareholders on August 13, 2024.Treasure Global (TGL) -24.56%
Friday’s pullback followed Tuesday’s sharp rally. The stock still ended the week above the previous Friday’s close.
Questo pezzo era gratuito. Il prossimo arriva domenica.This piece was free. The next one lands on Sunday.
Ogni domenica analizziamo fino a dieci titoli e pubblichiamo la lettura del mercato. L’abbonamento include tutte le analisi, i livelli operativi e le nostre posizioni in diretta nella chat. La parte gratuita arriva via email.Every Sunday, we analyze up to ten stocks and publish our market view. A subscription includes the full research, price levels and our live positions in the chat. The free section arrives by email.