
Win rate vs risk-reward: the trading expectancy formula
In short
Win rate is the percentage of trades closed at a profit, and on its own it can’t tell you whether a method makes money. You need expectancy: (win rate × average win) − (loss rate × average loss). With 70% winners of $20 and losers of $60 you lose $4 per trade; with 40% winners of $60 and losers of $20 you make $12. The break-even win rate is average loss ÷ (average win + average loss).
Between 1987 and 1993 the economist Terrance Odean studied the trades of 10,000 accounts at a US discount brokerage. His results, published in the Journal of Finance in 1998, showed a clear preference: when they sold, clients took gains far more readily than losses. A stock that was up was more than 50% more likely to be sold than one that was down.
That habit inflates a win rate. Winning trades get closed quickly and land in the win column; losing trades stay open, outside the count. The bill came later. Over the following twelve months, the winners those investors had sold beat the market by 2.35 percentage points, while the losers they had held trailed it by 1.06 points: a 3.4-point gap, all of it against the choice they made.
If your journal says you win seven times out of ten, that number still doesn’t tell you whether you are making money. You need two more numbers and a formula that ties them together. It is also the third of the four rules in our method, which we call probability: how often a setup has paid, how much it made when it worked and how much it cost when it didn’t.
What is win rate, and what does it measure?
Win rate is the number of trades closed at a profit divided by the total number of closed trades, after costs. Out of 100 trades, 70 winners give a 70% win rate. Decide once how to count trades closed at break-even and don’t change the rule halfway through.
Win rate measures frequency and nothing else. It says nothing about the size of gains and losses, and it depends heavily on how you set your exits. A close target and a distant stop push it up mechanically, because the price reaches the nearer level first. That is how two traders with the same win rate can have accounts heading in opposite directions.
What is the risk-reward ratio, planned and realized?
The planned risk-reward ratio compares the distance to your target with the distance to your stop. Enter at $50, stop at $49, target at $53: you risk $1 to make $3, a 3-to-1 ratio. It is an intention, written before you enter. The realized ratio only shows up in your journal: average win divided by average loss, on the trades you actually closed.
The two numbers almost always diverge. Partial exits, unfilled orders, early exits out of fear and gaps that jump the stop all change the result, and the differences between order types are in our guide to market, limit and stop orders. Keep plan and result in separate columns, or the attractive plan ends up standing in for the less attractive outcome.
A practical way to compare trades of different sizes is to express them in R, multiples of the planned risk. If you decided to risk $20 on a trade, $20 is 1R: a $60 gain is +3R, a loss at the stop is −1R, a $28 loss on a gap is −1.4R.
How do you calculate expectancy? A 100-trade example
Before you look at the table, pick one. Would you rather have record A, which wins 70 times out of 100, or record B, which wins 40 times out of 100? Keep your answer in mind.
A has 70 winners averaging $20 and 30 losers averaging $60. B has 40 winners averaging $60 and 60 losers averaging $20. These are hypothetical inputs. Assume zero costs for this first comparison; we add costs below.
| Record | Win rate | Average win | Average loss | Total gains | Total losses | Net result | Expectancy |
|---|---|---|---|---|---|---|---|
| A | 70% | $20 | $60 | $1,400 | $1,800 | −$400 | −$4 |
| B | 40% | $60 | $20 | $2,400 | $1,200 | +$1,200 | +$12 |
Expectancy is the average result a method produces per trade. The formula: (win rate × average win) − (loss rate × average loss). For A: 0.70 × 20 − 0.30 × 60 = 14 − 18 = −$4. For B: 0.40 × 60 − 0.60 × 20 = 24 − 12 = +$12. Multiplied by 100 trades they give exactly −$400 and +$1,200. If the averages are already net, don’t subtract costs a second time.
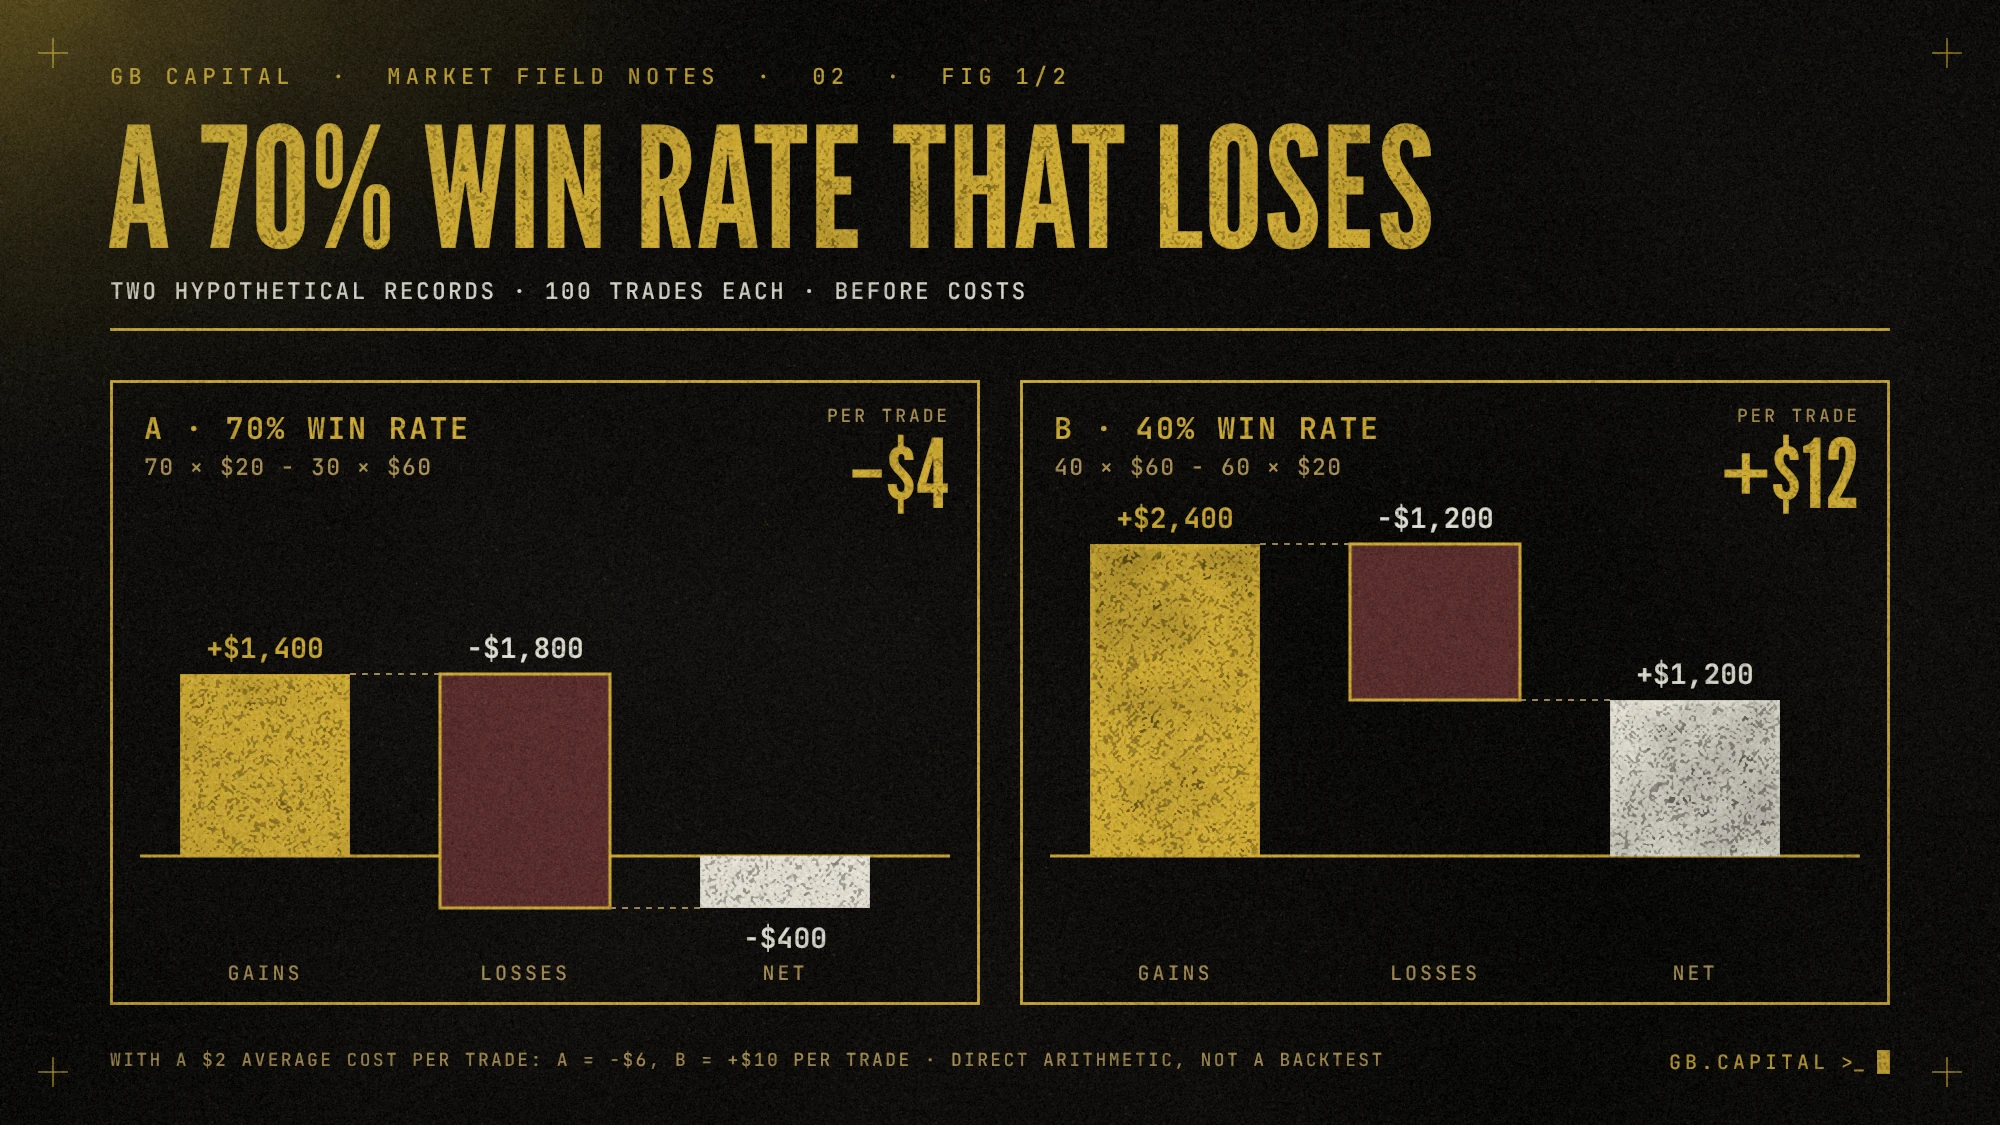
In R, B’s numbers get easier to read. If every trade risked $20, the average win is 3R and expectancy is 0.40 × 3 − 0.60 × 1 = +0.6R per trade. Another useful measure is the profit factor, gross gains divided by gross losses: 2,400 ÷ 1,200 = 2 for B, 1,400 ÷ 1,800 = 0.78 for A. Below 1, a method loses money whatever its win rate.
What is the break-even win rate?
The break-even win rate comes from your realized averages: average loss ÷ (average win + average loss). For B it is 20 ÷ 80 = 25%: winning 40% of the time gives it a 15-point cushion. For A it is 60 ÷ 80 = 75%: winning 70% leaves it 5 points short, which is why it loses.
| Average win ÷ average loss | Break-even win rate |
|---|---|
| 0.5 to 1 | 66.7% |
| 1 to 1 | 50% |
| 1.5 to 1 | 40% |
| 2 to 1 | 33.3% |
| 3 to 1 | 25% |
| 4 to 1 | 20% |
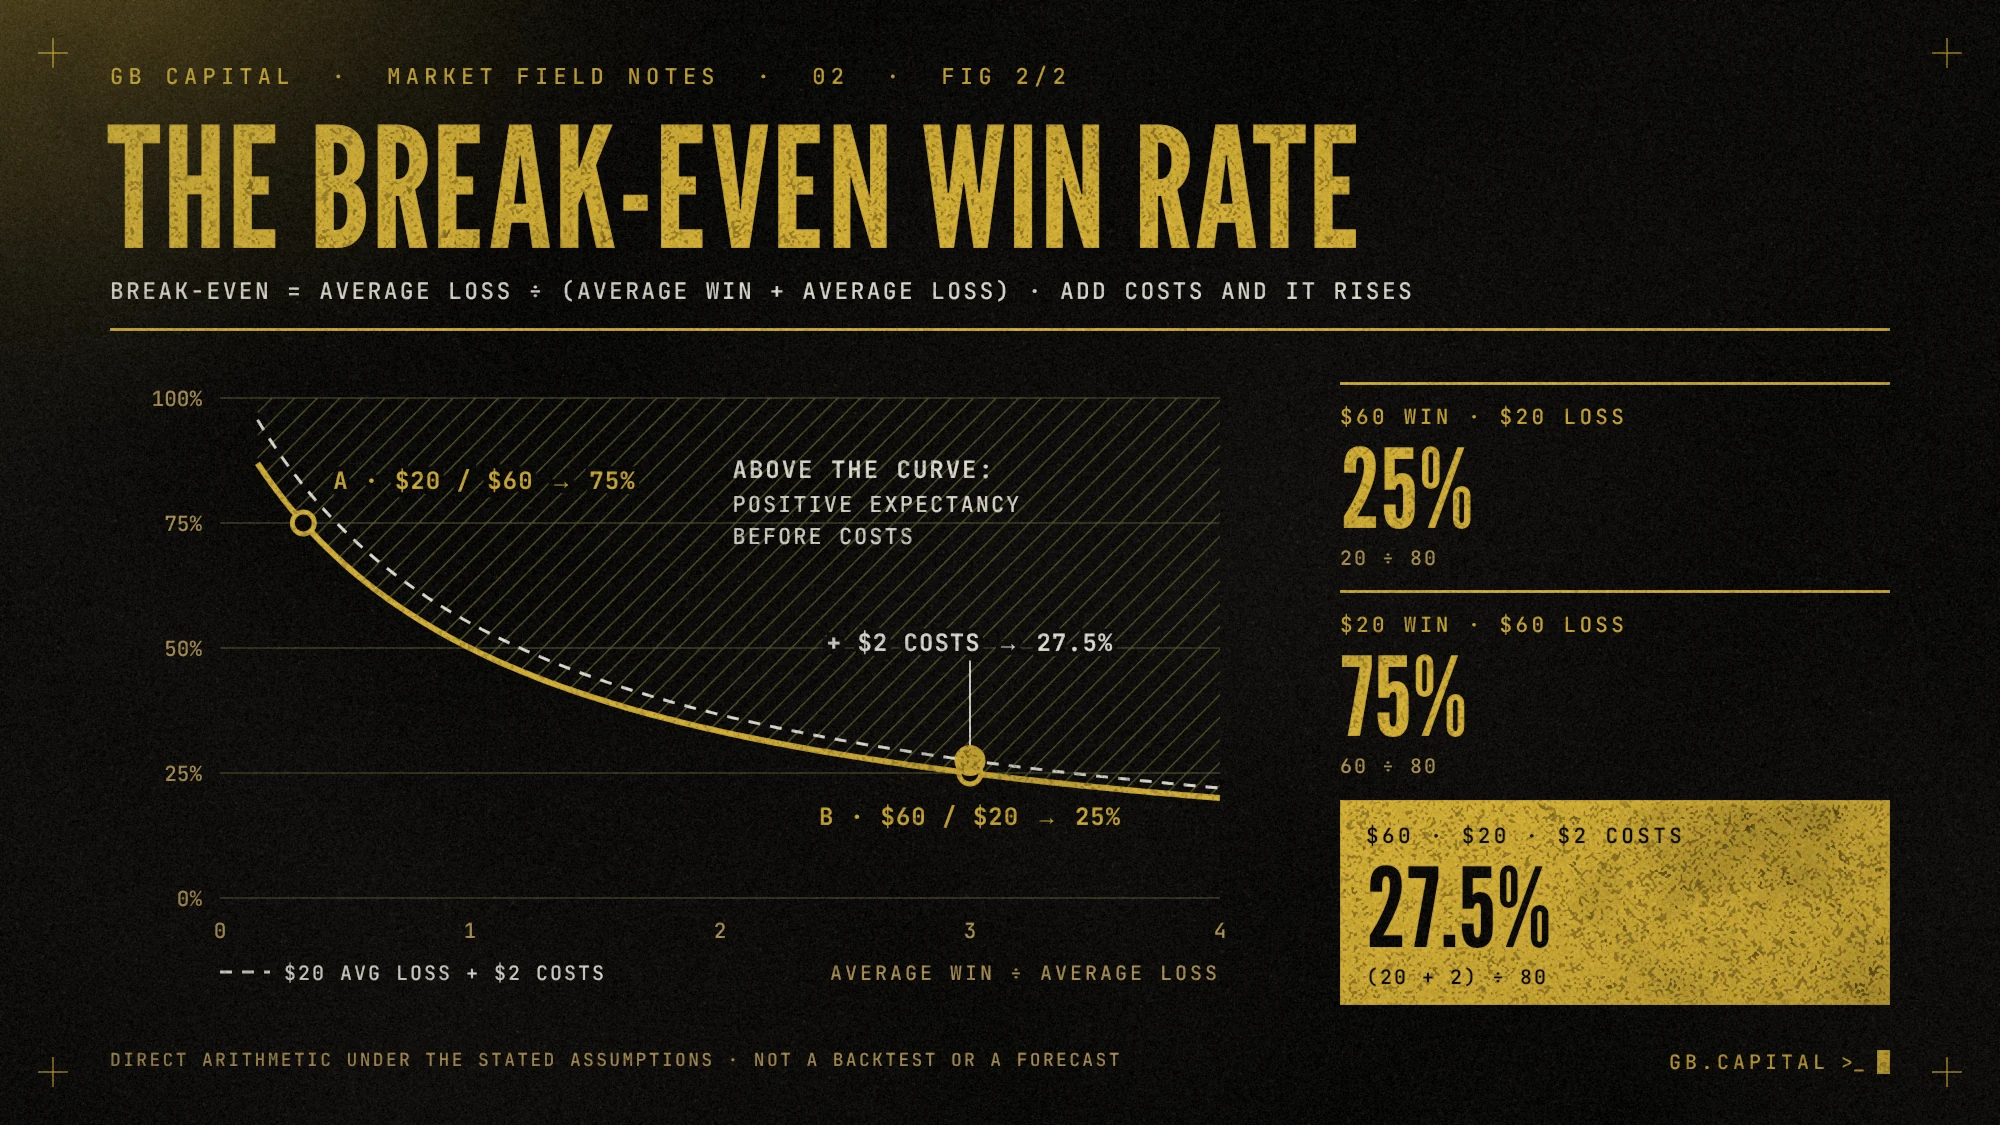
The threshold moves with the averages, and it moves fast. If B starts taking profits too early and its average win drops from $60 to $30, with the average loss still at $20 the threshold climbs from 25% to 40%. That is exactly its win rate: 40 wins of $30 make $1,200, the same as 60 losses of $20, and the record ends at zero. The same habit Odean measured in the broker’s clients is enough to wipe out an edge.
Why doesn’t a high win rate prove anything on its own?
Big losses outweigh small wins
Take a hypothetical method that wins 80 times out of 100 with average gains of $20 and loses the other 20 times by $50: it ends at +$600. Let just one of those 20 losses turn into $1,000, through a moved stop or a gap, and the total drops to −$350. The win rate is still 80%. How a single loss left to run stretches out the recovery is covered in our guide to drawdowns.
Ten trades are not enough
Suppose your true win rate is 50%. Over 10 trades, the probability of seeing at least 7 winners by pure chance is 17.2%. Over 30 trades, the probability of seeing 60% or more is still 18.1%, and only over 100 does the probability of reaching 70% fall to 0.004%. These figures assume independent trades. Even hundreds of trades, if they all come from one favorable market stretch, can describe the next stretch badly, which is why your trading journal should keep the dates and record every trade, including the ones you would rather forget.
The plan is not the result
Logging planned targets instead of actual exits, or omitting commissions, produces a risk-reward ratio different from the one realised. Calculate the break-even threshold from actual net averages and retain the trades used to derive them.
Why can the same result come with different drawdowns?
Two records can hold the same wins and losses in a different order. The total matches and the path of the account changes. In the figure, B’s 100 trades, written in R (40 wins of +3R, 60 losses of −1R), appear in two sequences. Both end at +60R. In the first, the account never falls more than 6R below its high; the second opens with 10 losses in a row and touches −10R.
With a 40% win rate and independent trades, the probability of hitting at least one streak of 10 consecutive losses in 100 trades is about 20%. If you risk 1% of the account per R, ten straight losses mean a 9.6% decline: the point where it is easiest to abandon a method that, over the same 100 trades, finishes at +60R. How much to risk so you don’t reach that point with a damaged account is in our guide to position sizing.
Check extreme results individually. Recalculate expectancy without the largest win, then without the worst loss, labelling these as additional checks. The complete result still includes every trade. A 55-minute 1:1 session on your process, with a written summary, can also be used to discuss these numbers.
The two-outcome break-even formulas assume every trade is either a winner or a loser. When the log includes exactly zero net outcomes, multiply the J8 threshold by the fraction of nonzero trades: (winners + losers) ÷ J2. J3 remains winners ÷ all trades. This keeps the comparison consistent; the mean of all net outcomes in J6 already includes zeros. With no winners or no losers, avoid dividing by zero and leave the threshold unavailable.
Include costs in the break-even win rate
For gross average wins and losses, break-even win rate = (average loss + average round-trip cost) ÷ (average win + average loss). With $60 winners, $20 losers and $2 costs, the threshold is 22 ÷ 80 = 27.5%, rather than 25% before costs. At a 40% win rate, expectancy becomes $10 per trade. If the journal already records net results, do not deduct the same costs again. Use the same completed-trade sample and currency for every input.
Frequently asked questions
What is a good win rate in trading?
It depends on the ratio of average win to average loss. With wins three times larger than losses, anything above 25% is enough; with wins half the size of losses, you need more than 66.7%. A win rate should always be read next to its break-even threshold.
How do you calculate trading expectancy?
Multiply the win rate by the average win and subtract the loss rate multiplied by the average loss. With 40% winners of $60 and 60% losers of $20: 0.40 × 60 − 0.60 × 20 = +$12 per trade. In a spreadsheet, the average net result of all your trades gives the same number.
What risk-reward ratio do you need to be profitable?
No ratio is enough on its own. A realized 3-to-1 requires winning more than 25% of the time, a 1-to-1 more than 50%. What counts is the realized ratio in your journal, which is usually lower than the planned one because of early exits, gaps and costs.
How do you calculate the break-even win rate?
Divide the average loss by the sum of the average win and the average loss, using averages net of costs. With an average win of $60 and an average loss of $20: 20 ÷ 80 = 25%. If the average win falls to $30, the threshold rises to 40%.
What is profit factor?
It is the ratio of total gains to total losses over a set of trades. Above 1 the method has made money, below 1 it has lost: $2,400 of gains against $1,200 of losses gives a profit factor of 2.
How many trades do you need to evaluate a strategy?
More than thirty, and often many more. With a true 50% win rate, there is a 17.2% chance of winning at least 7 of 10 trades by luck, and an 18.1% chance of reaching 60% over 30. Thirty trades are a minimum to start reading the numbers, and even a hundred can mislead if they all come from the same kind of market.
Sources and further reading
Keep company research separate from evidence about a strategy
An analysis of a business can explain why a stock deserves attention. It cannot, on its own, establish the expectancy of a trading method. That requires realised outcomes collected under comparable rules, including losses, fees and failed entries. If you use our company research to generate candidates, keep that step separate from the record used to evaluate your trades. The guide to recording trading decisions explains which information makes later comparisons possible. A persuasive thesis and a profitable sample are different kinds of evidence.