
Position sizing: formula and worked example for share count
In short
Position sizing is working out how many shares to buy from how much you accept losing if the trade goes wrong. The formula: shares = (account × risk %) ÷ (entry price − stop). With a $20,000 account, 0.5% risk ($100), an entry at $50 and a stop at $48, you buy 50 shares and commit $2,500. Capital committed, planned loss and the loss in a gap are three different numbers.
In 2016 Victor Haghani and Richard Dewey invited 61 quantitatively trained young adults to play a simple game. Each started with $25 and had 30 minutes to bet as much as they liked on flips of a coin that, as everyone was told, came up heads 60% of the time. Winnings were capped at $250.
With an edge that clear, the Kelly criterion (the formula for what fraction of your capital to bet when you know the odds) pointed to betting 20% of the balance on heads every flip. Twenty-eight percent of the players went bust. Only 21% reached the $250 cap, and the average payout was $91. Eighteen people bet their whole bankroll on a single flip at least once.
Trading poses the same problem, with one difference: you are never told whether your coin is rigged, or by how much. You find out whether a method has an edge after hundreds of trades, and to get there the account has to survive the losing streaks along the way. This guide gives you the formula for how many shares to buy, the three numbers to write down before every order and a calculator you can copy.
What is position sizing?
Position sizing determines how many shares to buy from the loss you are willing to accept. Starting instead with available cash ('I have $5,000, so I can buy 100 shares at $50') or conviction in the idea can leave the quantity disconnected from the planned loss.
Every position also carries three numbers that need to stay separate. Capital committed is the money that leaves the account to buy: shares × price. Planned loss is what you lose if you exit at the stop: shares × (entry − stop), plus costs. Gap loss is what you lose if the price jumps over the stop and you get out lower. Calling a $2,500 position “a $100 risk” is only accurate if you also write down where you plan to exit and accept that the market may let you out somewhere else.
How do you calculate position size? The formula
The basic method is called fixed fractional: on every trade you put the same fraction of the account at risk, recalculated on its current value. The formula is: shares = (account × risk %) ÷ (entry price − stop).
Try it before you read the answer. You have a $20,000 account, you decide to risk 0.5% on this trade, you enter at $50 and put the stop at $48. How many shares do you buy? Write the number down.
The risk budget is 20,000 × 0.005 = $100. Each share loses $2 if you exit at the stop. So 100 ÷ 2 = 50 shares, committing $2,500, 12.5% of the account. If you wrote 400, you divided the whole account by the price: that is the quantity of someone who puts in everything they have, and with the stop at $48 it would risk $800, 4% of the account.
The distance to the stop moves the quantity far more than most people expect. With the same $100 budget:
| Stop | Risk per share | Shares | Capital committed | Share of account |
|---|---|---|---|---|
| $49 | $1 | 100 | $5,000 | 25% |
| $48 | $2 | 50 | $2,500 | 12.5% |
| $47.50 | $2.50 | 40 | $2,000 | 10% |
| $46 | $4 | 25 | $1,250 | 6.25% |
| $45 | $5 | 20 | $1,000 | 5% |
In all five rows the planned loss is $100. A tight stop produces a big position, a wide stop a small one. The stop belongs where the chart says the idea is wrong, and the quantity adjusts to it. Pulling the stop closer so you can buy more shares only makes it more likely to get hit.
How do you include costs and available cash?
The $100 also has to cover commissions, the spread and, if your account is in another currency, the currency conversion. Assume $6 of total costs across entry and exit. That leaves $94 for the price distance: 94 ÷ 2 = 47 whole shares, committing $2,350. An exit exactly at $48 costs $94 on price plus $6 of costs, $100 in all. How to estimate those costs is covered in our guide to trading costs. If commissions or conversion depend on quantity, replace the fixed amount with your broker’s calculation.
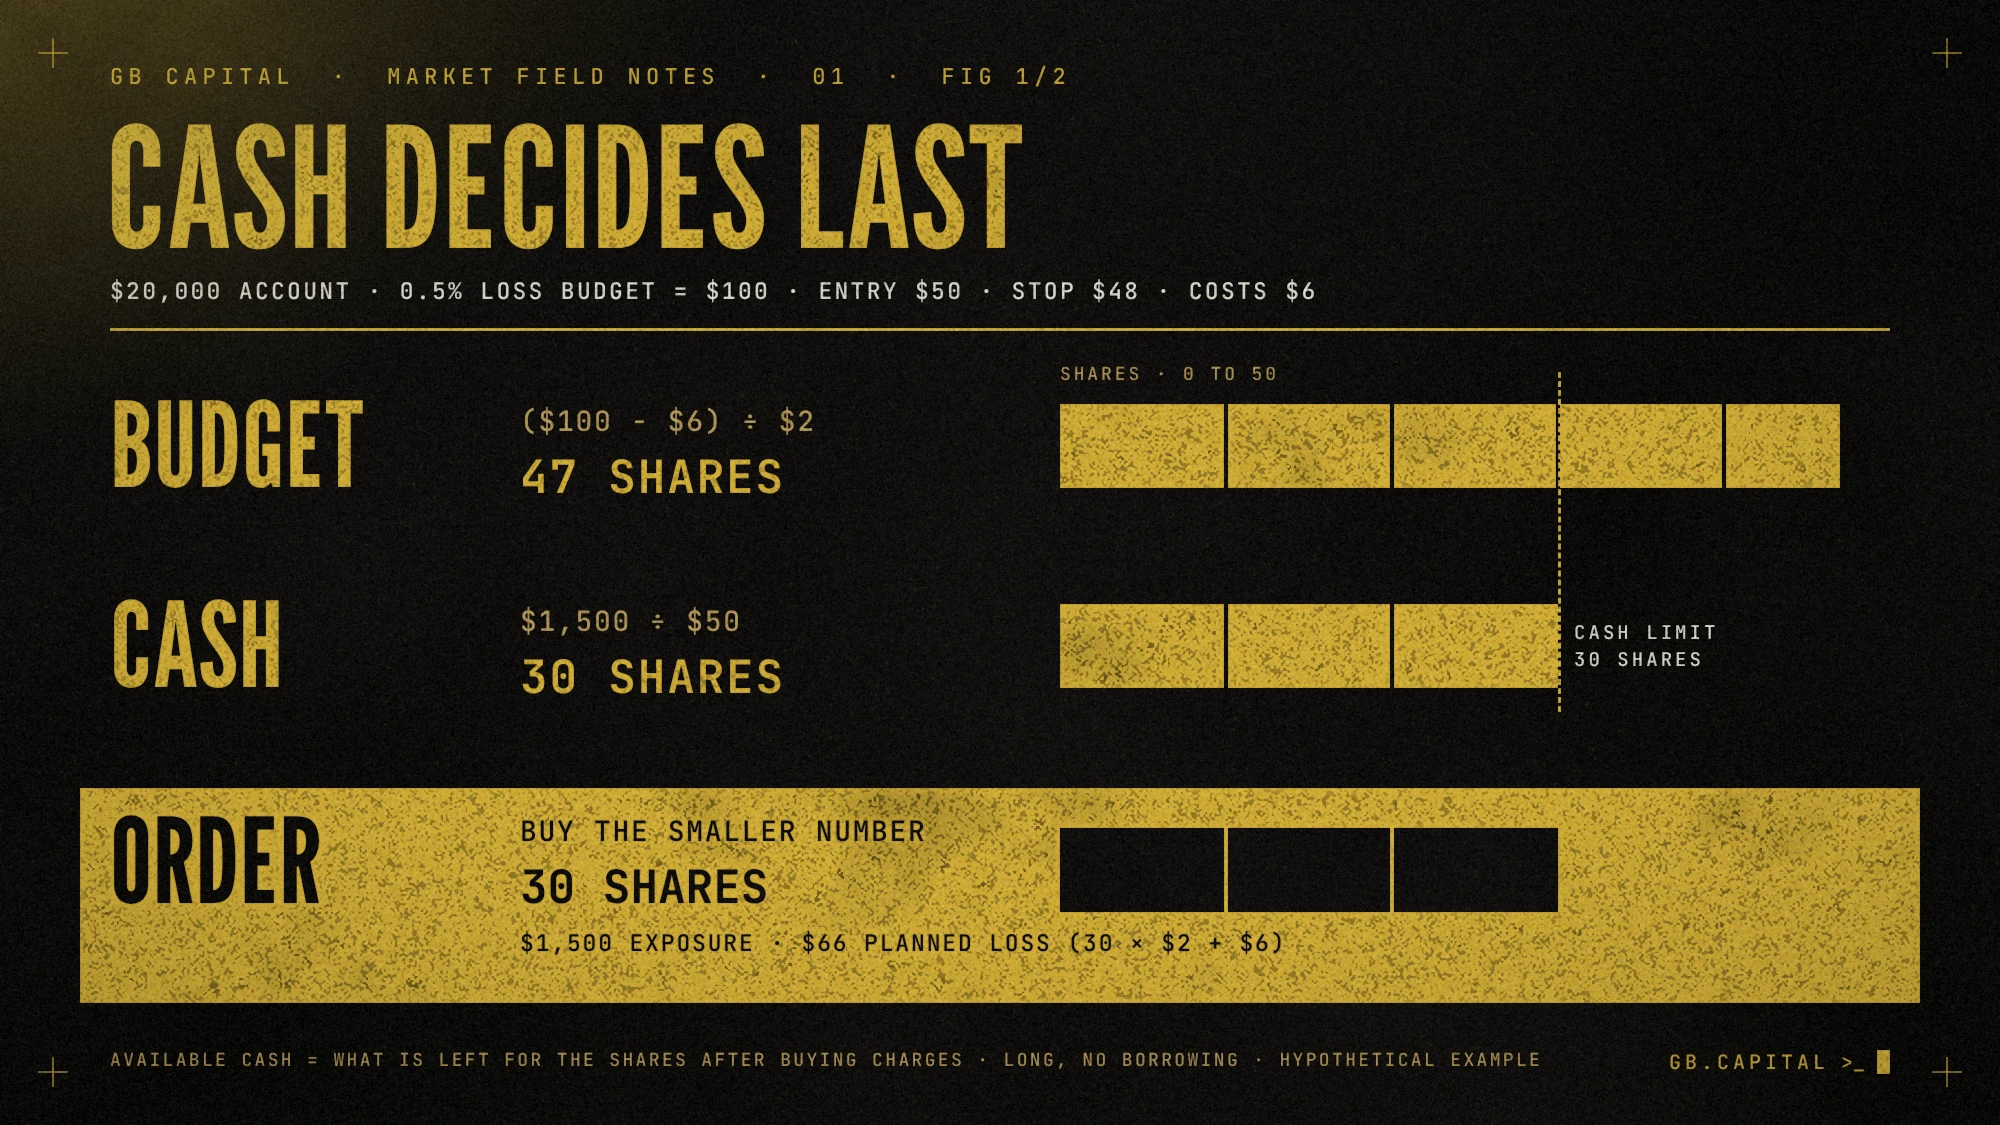
The second limit is cash. If you only have $1,500 free, at $50 you can buy 30 shares at most, before costs. The final quantity is always the smaller of the risk number and the cash number. The risk budget never justifies using margin, money borrowed from your broker, to reach 47 shares.
A warning for anyone using instruments with a multiplier. One US equity option contract usually covers 100 shares, and futures have their own multipliers: the same per-unit math comes out a hundred times off if you forget the multiplier. Write down the instrument’s specifications before doing the arithmetic.
What happens to the loss if the price jumps the stop?
The $100 assumes an exit at $48. A stop turns into a market order when the price reaches or crosses it, and on a gap open it fills at the first available price. If the stock opens at $45, the same 47 shares lose $235 on price, $241 with costs: 2.4 times the plan. If it opens 20% lower after an earnings report, at $40, the loss climbs to $476. The mechanism is explained in our guide to earnings gaps and overnight risk.
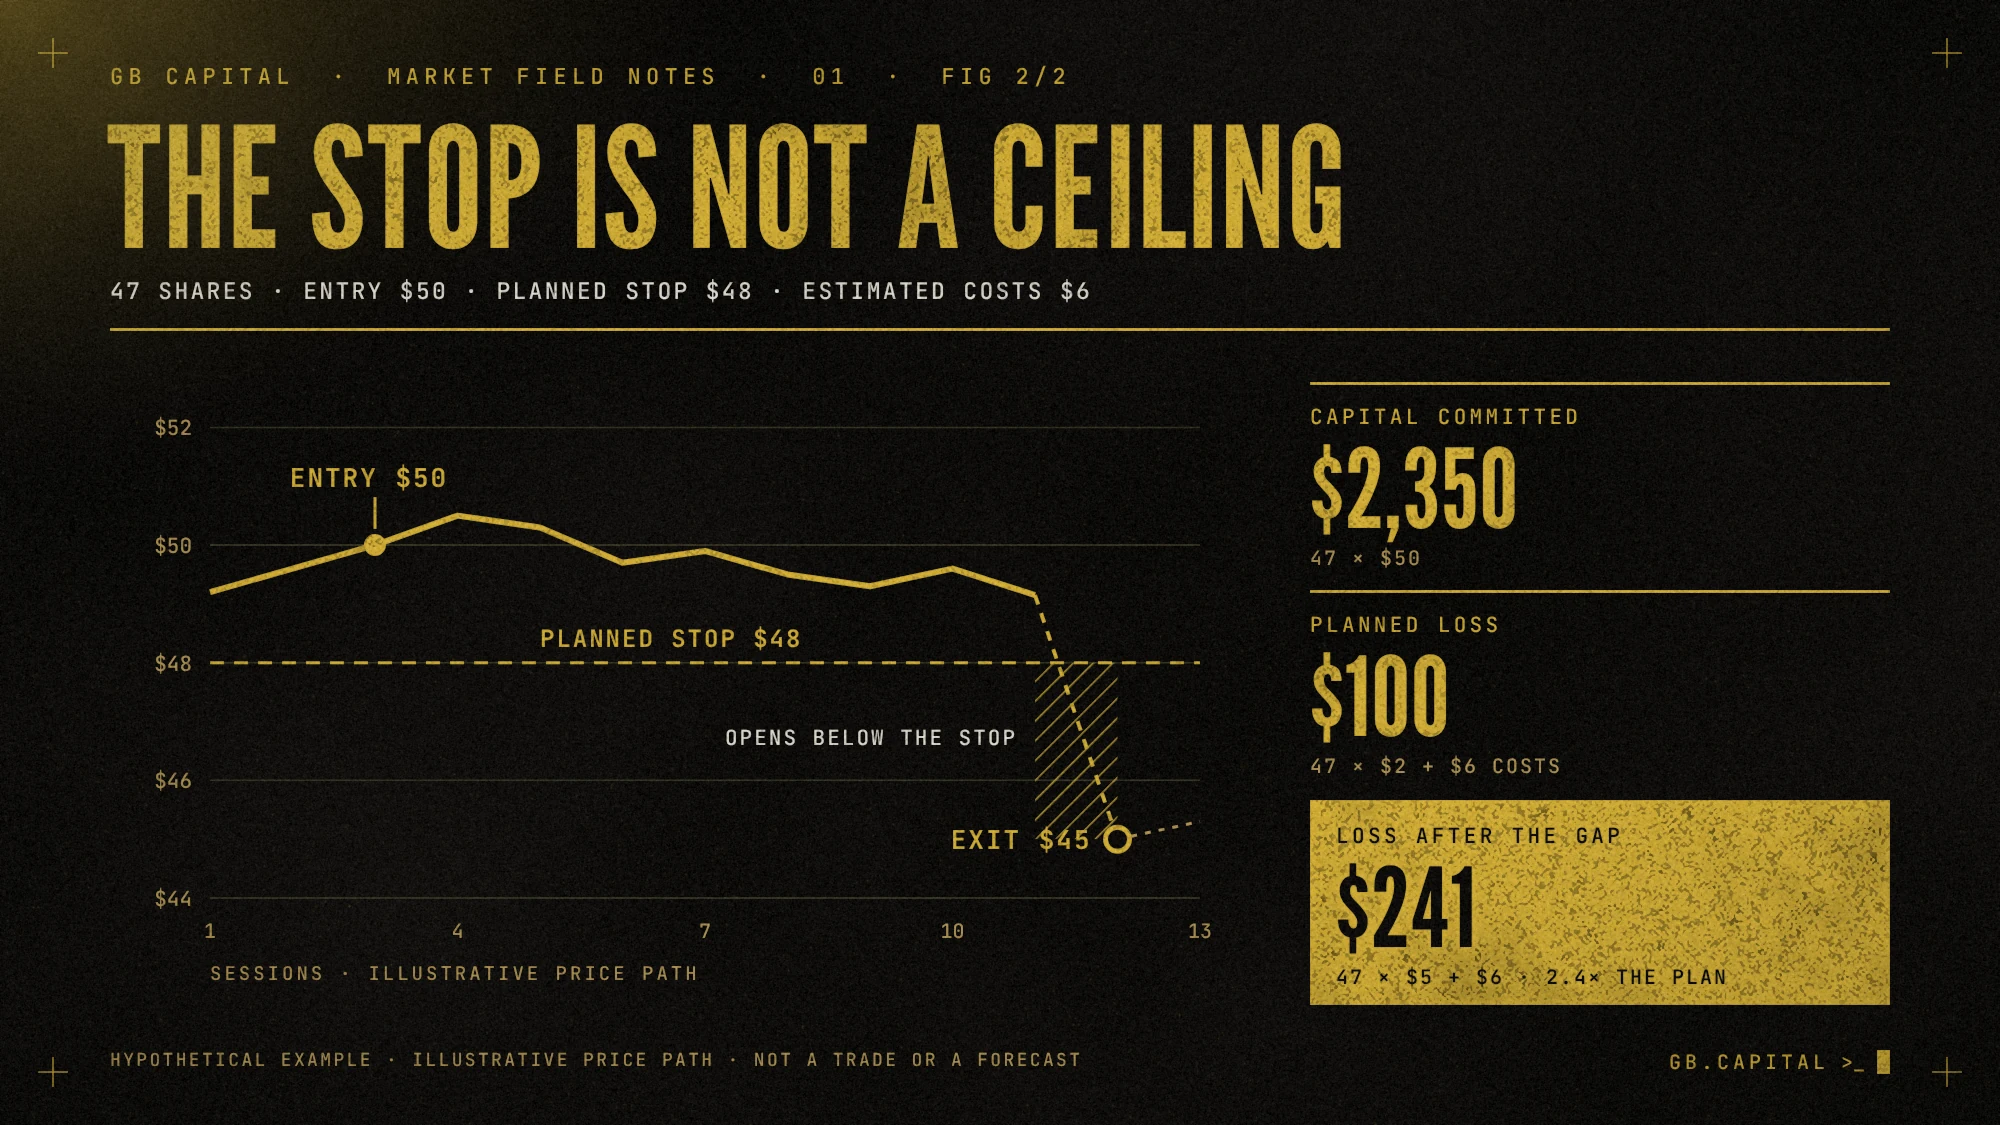
The quantity stays at 47 in each scenario; the actual exit price changes. Before placing the order, calculate the loss at a worse exit too. If that exceeds what you are willing to accept, revisit the quantity rather than relying only on the stop level marked on the chart.
How much should you risk per trade?
There is no percentage that fits everyone, and the 0.5% in the example is a teaching number. To see what each choice implies, look at what a run of consecutive losses does. With fixed fractional risk, ten losses in a row take a $20,000 account to $18,088 at 1% per trade, $16,341 at 2%, $11,975 at 5% and $6,974 at 10%. Breaking even from there takes 10.6%, 22.4%, 67% and 186.8% respectively.
Ten losses in a row sound extreme. We calculated how often they happen, assuming independent trades and a constant win rate. With a 40% win rate, over 200 trades the probability of at least one streak of 10 consecutive losses is 38%, and of a streak of 8 it is 75%. With a 50% win rate the two figures drop to 9% and 32%. Anyone running a method with few winners and large gains has to size for those streaks. How win rate, risk-reward and expected result fit together is in our guide to win rate and expectancy, and the recovery math is in the one on drawdowns.
The Kelly criterion used in the coin experiment calculates the optimal bet when the odds and payoffs are known precisely. Trading relies on estimates. Overestimating an edge can produce oversized bets.
How do you add up risk across positions?
Five positions with a planned loss of $100 each add up to $500, 2.5% of the account, if they all hit their stops. The arithmetic is simple; the mistake is treating them as independent. Five stocks in the same sector, or exposed to the same event, tend to fall together, and on a bad day they behave like a single $500 position. How to measure that hidden exposure is in our guide to correlation and diversification.
If your account is in euros or another currency and you buy US stocks, write every amount with its currency. A $100 planned loss is worth a different amount in your home currency depending on the exchange rate, and adding up figures in different currencies by accident distorts the whole risk picture.
In the calculator, B7 is available cash after reserving entry costs. The example’s $1,500 is net of that reserve: if it is a gross balance, subtract purchase commissions and conversion costs first. B4 must exceed B5 and B9 must cover B6; otherwise the permitted quantity is zero. Do not include the spread in B6 again when it is already reflected in execution prices.
When cash is the tighter limit
With $1,500 available for shares after reserving entry costs, you can buy 30 shares at $50. With a planned exit at $48 and $6 in total costs, planned loss is $66: 30 × $2 + $6. If fees vary with quantity, recalculate them before confirming the cash and loss limits.
Frequently asked questions
How do you calculate position size?
Multiply the account value by the percentage you accept losing, then divide the result by the distance between entry price and stop. With $20,000, 0.5% risk, an entry at $50 and a stop at $48: 100 ÷ 2 = 50 shares. If there are costs, subtract them from the budget before dividing.
What is the 1% risk rule?
It is the convention of losing no more than 1% of the account on a single trade if the stop is filled. It refers to the planned loss: with $20,000 it means risking at most $200, even if the position commits $5,000. It is a convention, and the right percentage depends on your method and on the losing streaks you can sit through.
What is the difference between position size and risk?
Size is how much money you commit: shares times price. Risk is how much you lose if you exit at the stop. A $2,500 position with a stop 4% below the entry risks $100; the same position with a stop 20% below risks $500.
How many shares can I buy with $10,000?
It depends on the stop more than on the capital. With $10,000 and 1% risk, the budget is $100: with a stop $2 from the entry you buy 50 shares, with a stop $5 away you buy 20, as long as the cash covers it. The share price only matters for the cash limit.
Does position sizing protect you from gaps?
No. The planned loss assumes the stop fills at its level, and on a gap open the price can jump right over it. For positions held through an earnings report, also calculate the loss under a stress gap and cut the quantity if that number exceeds what you accept.
What is the Kelly criterion?
It is a formula for what fraction of your capital to bet when you know the probability of winning and the payoff. For an even-money bet that wins 60% of the time it gives 20%: 0.60 − 0.40 = 0.20. In trading, odds and payoffs are only estimates, and an optimistic estimate leads to oversized bets.
Sources and further reading
Before you size the trade, check what can move it
The formula above begins with an entry and a planned exit. Before using it on a company in our archive, write down the next earnings date and any event that can move the price outside trading hours. Then calculate the loss at a worse exit price as well as at the stop. Neither number is a guarantee; together they make the exposure easier to judge. A list of candidates becomes useful only when it includes those constraints. The guide to building a stock watchlist explains what to record before a candidate becomes a position.