Wall Street Radar Vol. 101: Stocks to Watch
Volume 101
The Right Wave
The hardest part of surfing was never spotting the right wave.
It’s catching the exact one you spotted at the right half second. Every surfer learns, usually the hard way, that these are two separate skills that feel like one from inside the water. Misjudge the first and you paddle for nothing. Misjudge the second, on a wave you read perfectly, and you pearl: the nose digs under, the board stalls, and the wave built for you throws you over instead of carrying you anywhere.
We have to be honest about which one has been happening to us.
We’ll be straight about it: the selection has been good. SKHY, PURR, FPS, three names picked out of the noise over the past weeks, and all three did exactly what we expected. Up ten to fifteen percent in a handful of sessions, which is what a correctly read wave looks like. Then volatility rolled through, and we closed out breakeven, or with a small loss, before any of it could pay off.
The wave was chosen correctly. We pearled anyway.
The watchlist remains, in our view, one of the strongest things we put out every week, and the stock selection underneath it isn’t the problem. Timing is, and it’s where we’re putting the real work right now.
(Follow the picks. Our timing, maybe not yet!)
Part of why it slipped isn’t a mystery. The last few months carried some personal weight and some business weight at the same time, and some of the shine from the first part of the year went with it. We’d rather tell you that directly than let the numbers say it for us.
The other part is that there’s simply more water to read than there used to be.
Still three people. Research and trading come first, every day, not up for negotiation, and what reaches you has to stay exactly where it’s always been.
Everything else gets built around that, not instead of it.
You’ll remember we mentioned a business trip to France. It went well, better than expected, and there’s more coming out of it before the year is done. Years running a company leave you with the instinct that every room is a chance to make clear what this newsletter and the research behind it are actually worth, and we haven’t lost that instinct.
Sorry for the long personal note. We think this should occasionally read like it was written by people, not filed as a report.
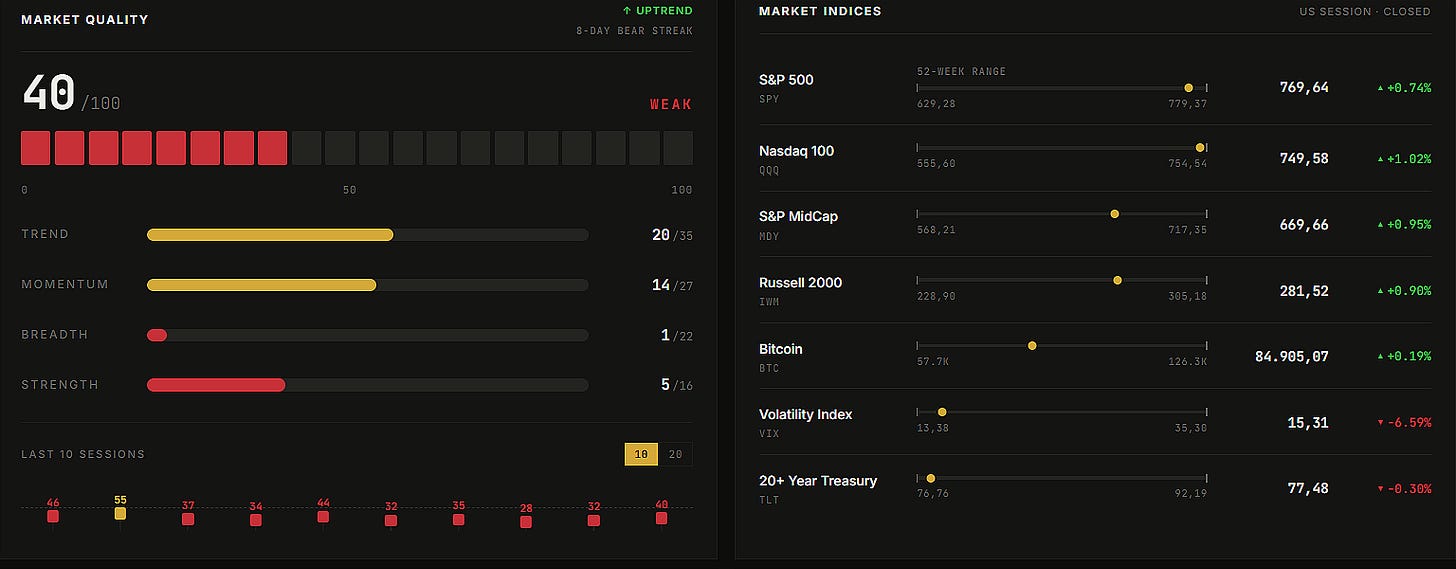
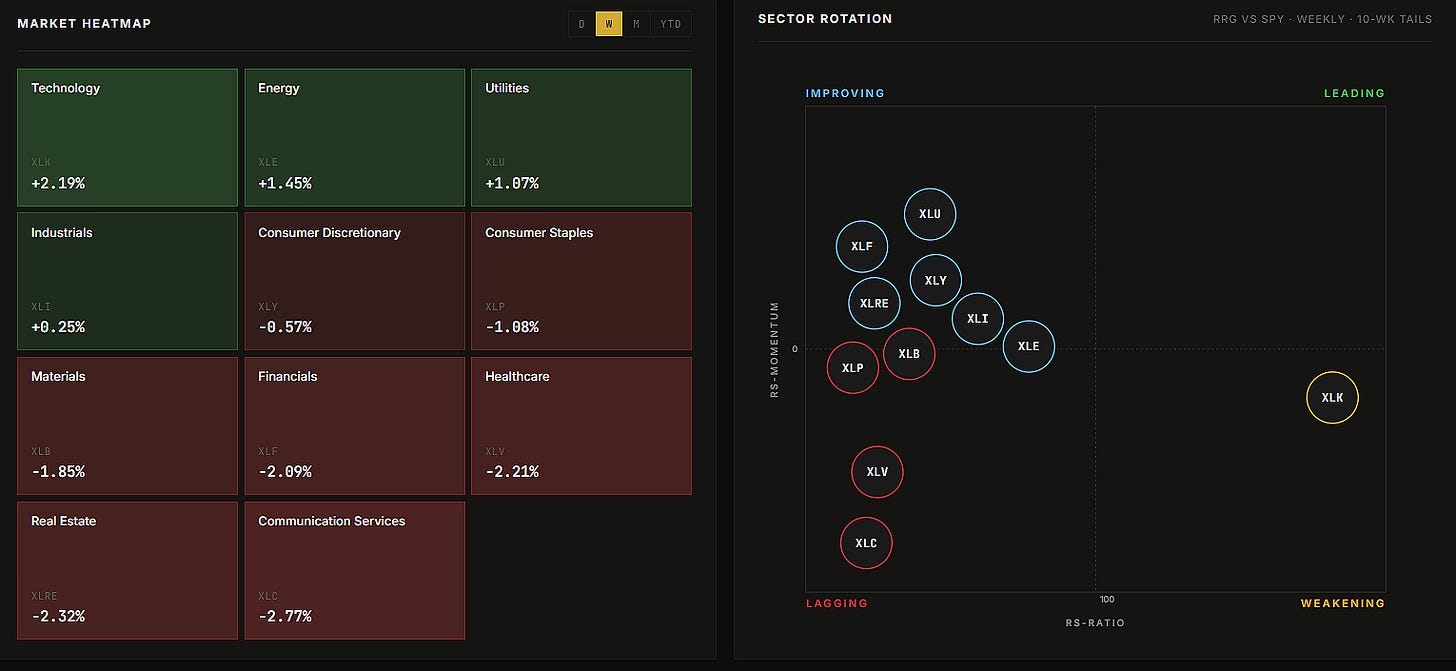
Here’s a look at this week’s market health, with a breakdown of index and sector performance.
📈 Free Setup: Make It Count
HONA: Honeywell Aerospace Inc
What they do: An aerospace and defence company
Why watch? Honeywell Aerospace did not go airborne after its spinoff. It went the other way, and its first earnings report as an independent company sent it straight to all-time lows.
The separation from Honeywell International, now trading as Honeywell Technologies, completed on 29 June 2026, and the company lists on the Nasdaq. It supplies avionics, navigation, engines, auxiliary power units, power and thermal systems and flight control products to commercial aerospace and defence customers, reporting through three segments covering Electronic Solutions, Engines and Power Systems, and Control Systems.
The revenue model is simple, and it has two halves that behave nothing alike. HONA earns money when equipment goes onto a new aircraft or defence platform, and it earns money again from parts, repair, overhaul, software and upgrades throughout that equipment’s operating life. The second half is where the profit lives. Selling a unit onto a new airframe is competitive and margin-thin, because airframers negotiate hard and suppliers accept it to secure the position. Servicing that same unit for the following three decades is neither competitive nor thin. The growth runway therefore reduces to the size of the installed base, meaning the amount of HONA equipment currently flying, because the more there is, the more maintenance events arise. When a component wears or reaches a service interval, the operator needs the correct part, the technical data, the repair procedure and certified support, and there is generally exactly one supplier who can provide all four. Electronic systems generate a parallel stream through software, compliance, safety and functionality updates.
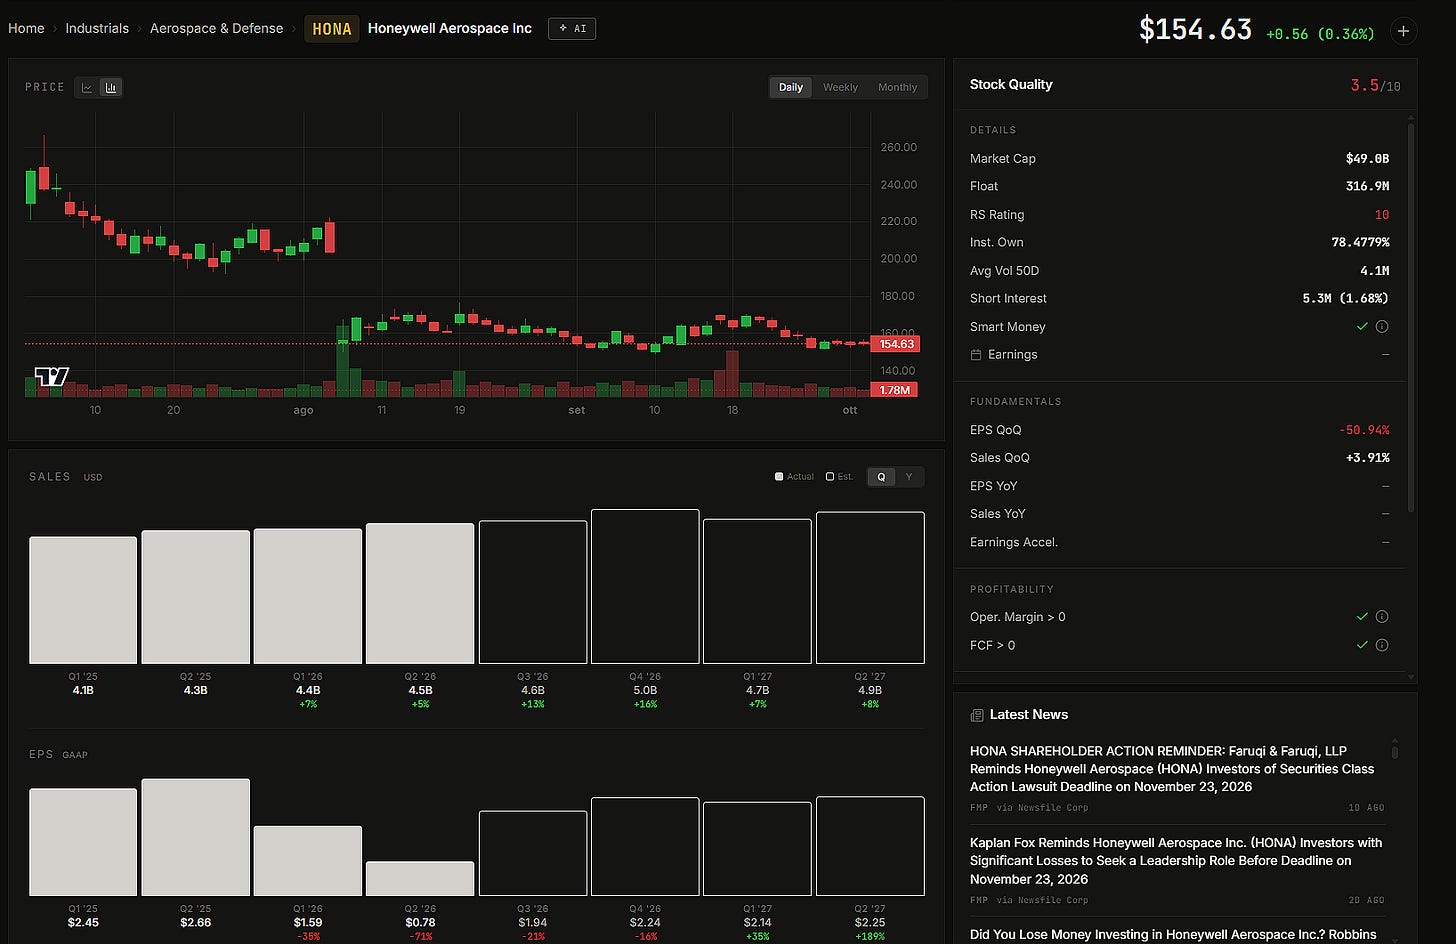
The 5 August report broke that logic in the short term. Second quarter sales were $4.5 billion, up 5% on both a reported and an organic basis. Adjusted EBIT came in at $995 million, down 7%. Adjusted earnings per share fell to $1.87 from $2.75, weighed down by roughly $100 million of separation costs and inventory obsolescence charges tied to the spinoff itself.
Then came the guidance, which is what actually did the damage. Full-year organic sales growth was cut to a range of 4% to 5% from a prior 7% to 9%, for a company that had projected 7% to 9% at its market debut barely five weeks earlier. Adjusted EBIT guidance came down by roughly $300 million at the midpoint, to between $4.35 billion and $4.45 billion. Second half free cash flow guidance was maintained.
The cause is not demand. Demand is fine. The constraint is precision castings, the specialty metal components that go into engines and mechanical systems, formed by pouring molten metal into moulds to tolerances that leave nothing to fix afterwards. Only a handful of suppliers are qualified to make them, because certifying a new one takes years, which keeps castings among the most structurally constrained inputs anywhere in commercial aerospace. HONA cannot produce enough parts, and when parts are scarce they have to go to Boeing and Airbus to keep production lines moving, because contractual obligations to the airframers come first. Every casting diverted to a new aircraft is a casting unavailable to the aftermarket, and the aftermarket is the high-margin business. That is the whole reason 5% sales growth produced a 7% decline in operating profit. Management acknowledged that corrective actions have taken longer than expected, particularly across the mechanical supply base, and is targeting a materially stronger 2027 as new suppliers, additional manufacturing capacity and tooling come online, having already added alternative sources across the constrained parts.
The underlying business does not appear broken. Commercial aftermarket increased 8% and Defense and Space sales grew 3%. A company with a growing aftermarket and an intact installed base working through a supply bottleneck is a different proposition from a company losing customers.
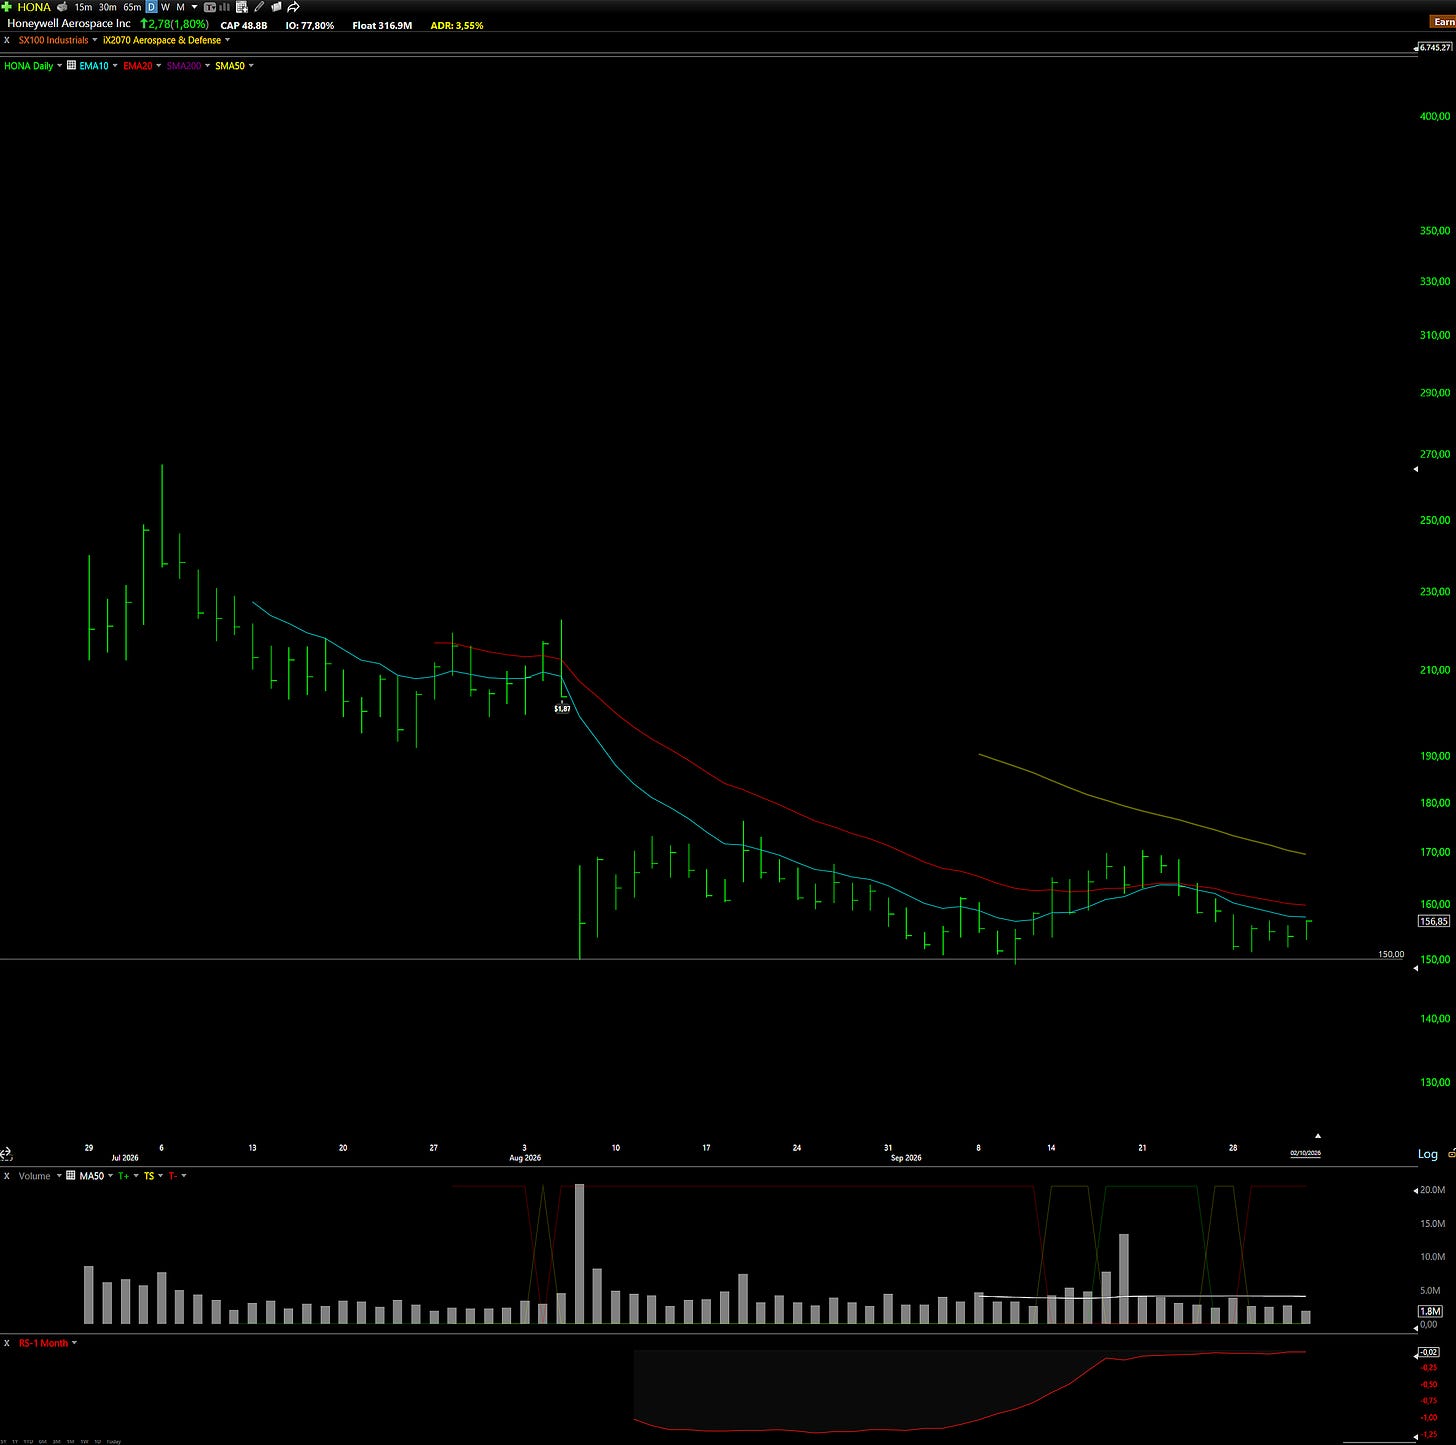
Technical Outlook: We wrote about this stock on 30 August with price near $150.00. It broke out, made a 10% move, and now we are back near $150.00 with a slightly higher low than the old setup. The stock is below all the key moving averages, but if it holds $150.00 firmly we think it has a good chance of going higher. The space sector performed well last week with SPCX leading the pack, and aerospace and defence moves with it, so if that initial group strength is confirmed over the next few weeks a good move can develop here with very good risk and reward.
What €39/month (or 299€/year) buys:
Free Access to TradeDeck
Premium members get full access to the trading platform we’re building. The value of the platform alone almost exceeds the cost of the subscription.
Watchlist Elite (5-7 Stocks)
Each selection undergoes rigorous financial analysis, technical evaluation, and strategic assessment.
Full Portfolio Transparency
Every position we hold. Entry price. Current P&L. Stop level. Real money, real risk.
Real-Time Portfolio ( and Chat Access)
This is where the edge lives. Exact entries, stops, and position sizing. Real-time..
The Tools We Actually Use
Member discounts on TC2000, FMP, and other platforms: same tools, better pricing.
What Paid Members Say:
Portfolio updates & Full Watchlist:
Il resto di questo pezzo: i nomi, i livelli, la gestione.The rest of this piece: the names, the levels, how we manage it.
Ogni domenica dieci titoli con i livelli scritti, la lettura del mercato e la chat in cui pubblichiamo entrate e uscite mentre le facciamo. Disdici quando vuoi dal tuo account Substack.Every Sunday, ten names with the levels written down, the market read, and the chat where we post entries and exits as we make them. Cancel any time from your Substack account.
Già abbonato?Already a subscriber? Apri l'articolo su Substack →Open the article on Substack →